Our Mission
Meet the Minds Behind Volatility Research
A small team of quantitative analysts and econometricians built this platform after years of
watching conventional risk tools miss the clustering that actually moves markets. They set
out to make latent regime detection accessible to serious practitioners.
- 12K+
- Research Hours
- 87%
- Model Accuracy
- 3Yrs
- Platform Growth
Total AUM
$ 450,000.00
- Research Fund $ 125,000.00
- Validation Pool $ 75,000.00
- Pilot Account $ 50,000.00
78%
Model Validation Score
Platform user growth driven by practitioner demand for regime-aware volatility
tools
Our Story
The project began in a university statistics lab where two doctoral students kept finding the same flaw: standard deviation models treated every day as independent, but markets remember. Volatility clusters. Regimes shift. The tools ignored both. So they built better ones.
2019
Year Founded
Published Papers
What started as academic frustration became a practitioner platform. The founders
watched risk managers rely on models that assumed yesterday's volatility told
you nothing about tomorrow's. They knew it did. After publishing their first
paper on latent regime detection in 2019, institutional researchers began asking for
the code. The platform grew from there — not through marketing, but through word of
mouth among quants who needed models that saw what others missed.
The Researchers Behind the Models
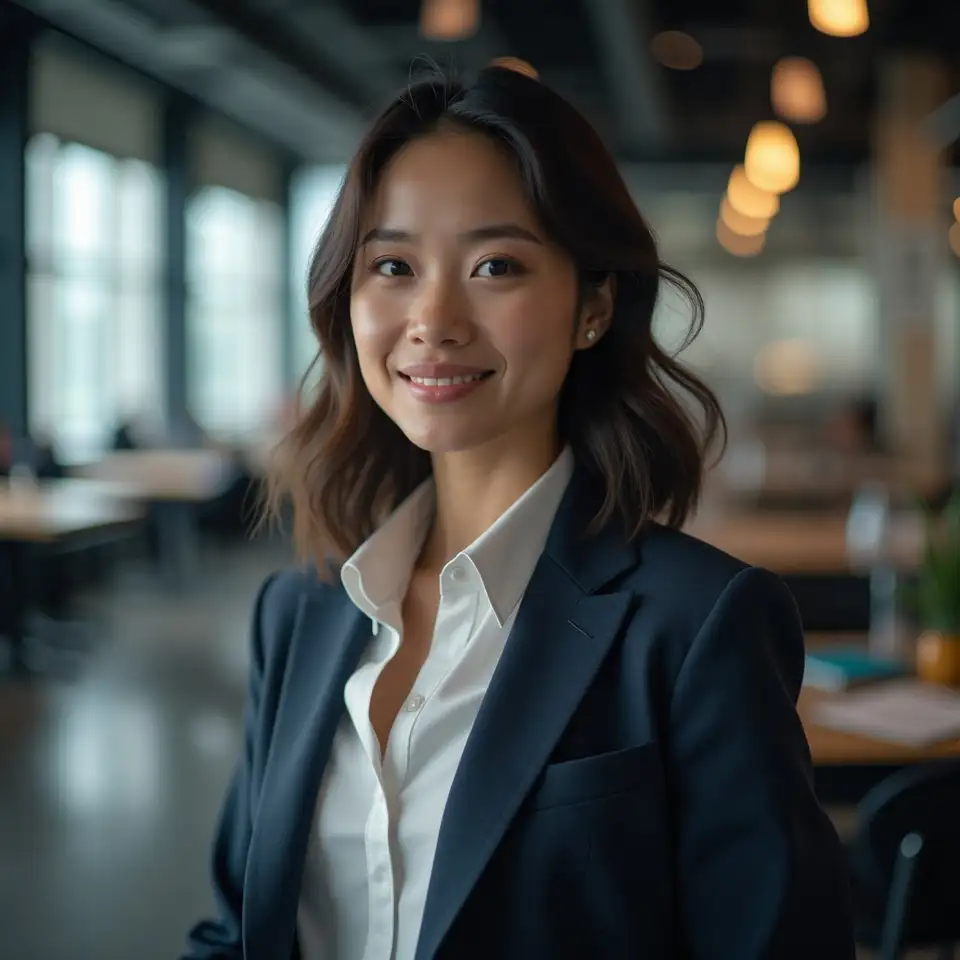
Dr. Elena Vasquez-Chen
Lead Quantitative Researcher
Elena completed her doctorate in statistical finance at the University of Auckland, where she developed novel Markov-switching models for volatility forecasting. Her dissertation on latent regime detection in emerging market indices won the faculty research prize in 2018. Before founding the platform, she spent four years advising central banks on stress-testing methodologies. She oversees all model development and validation protocols.
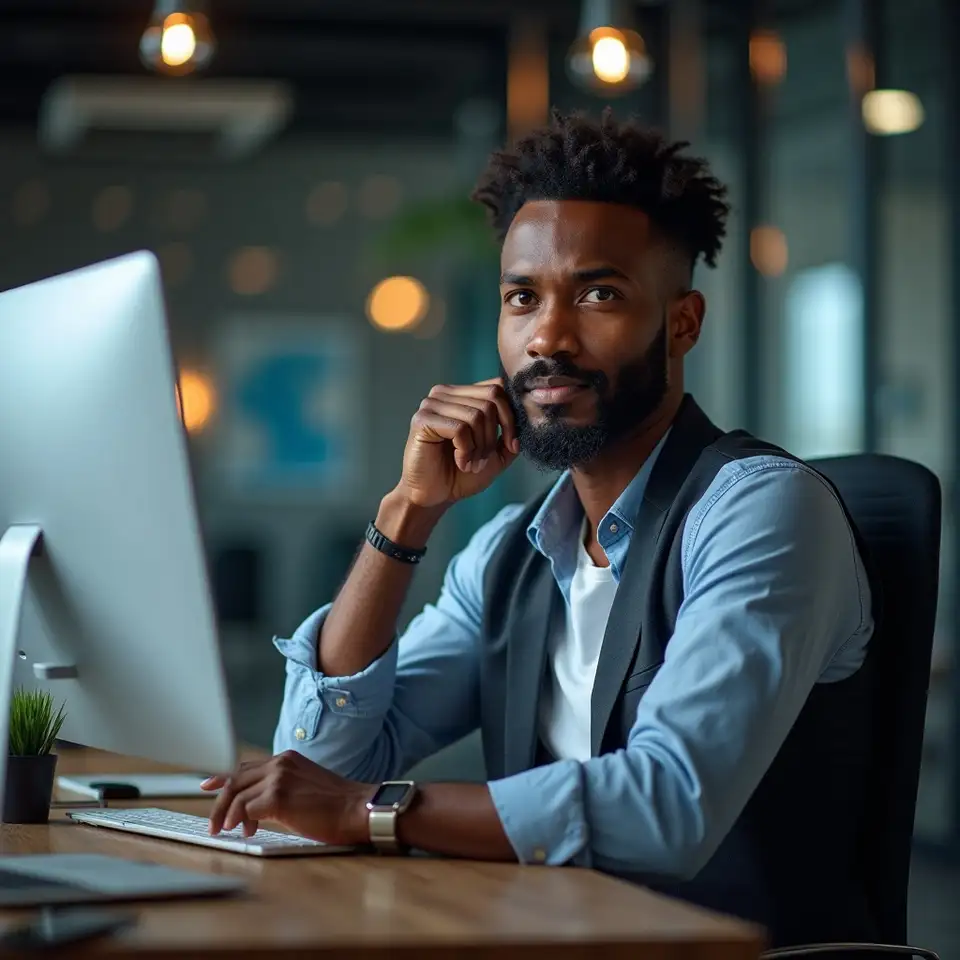
Marcus Whitfield-Okafor
Senior Econometrician
Marcus holds a master's in econometrics from Victoria University of Wellington
and spent six years building risk models for agricultural commodity derivatives. His
breakthrough came when he applied Hawkes process modeling to volatility clustering —
a technique now central to the platform's regime detection engine. He manages
the data pipeline and ensures every model output passes rigorous backtesting
standards before reaching users.
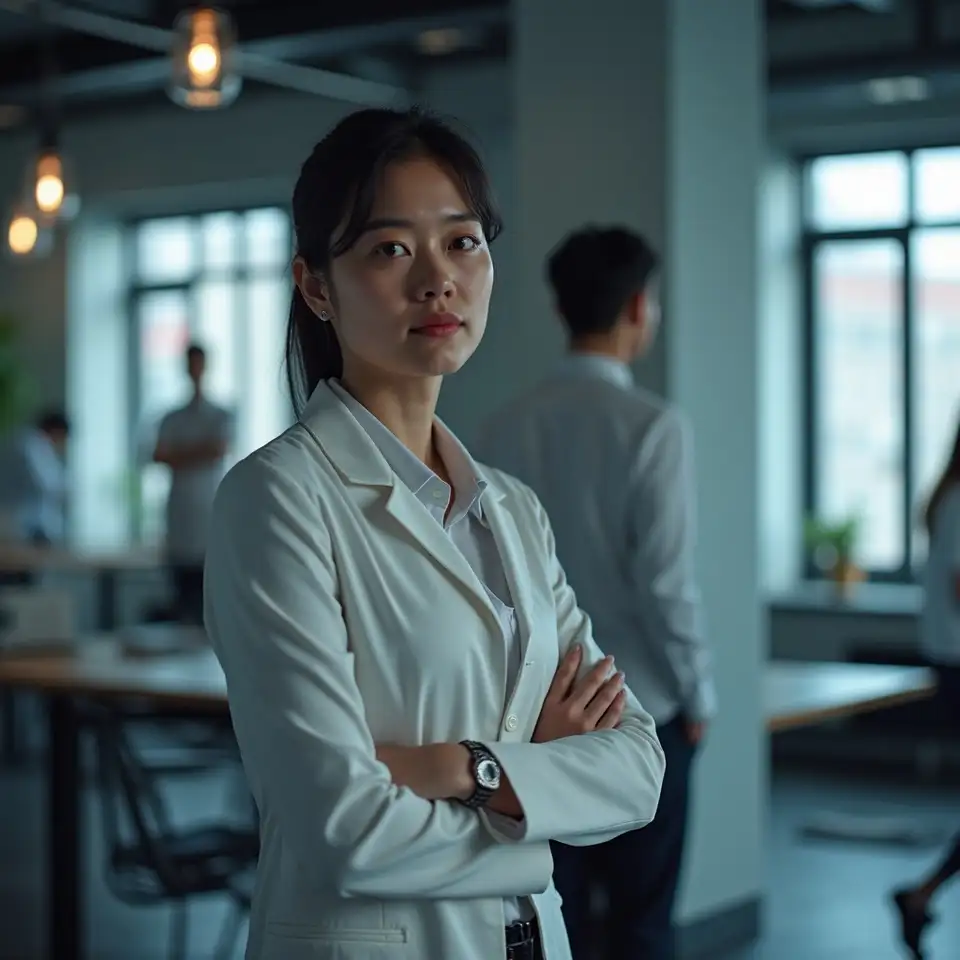
Dr. Yuki Tanaka-Richards
Head of Research OperationsYuki earned her PhD in applied mathematics from Kyoto University before relocating to New Zealand. She spent three years at a Wellington-based hedge fund optimizing execution algorithms, then returned to academia to study nonlinear time series dynamics. At the platform, she bridges the gap between theoretical model development and practical implementation, translating complex mathematics into tools that analysts can use without a doctorate.
How We Work
Four principles guide every model we build and every analysis we publish. They reflect what
the founders learned from years of watching bad tools fail and good tools go unused.
Intellectual Rigor
Every model faces hostile review before publication. The team stress-tests against
historical crashes, quiet periods, and regime transitions. If it breaks, it gets
fixed or discarded. No exceptions.
Method Transparency
Users see the assumptions behind every output. The platform hides nothing about model limitations, data sources, or parameter choices. Trust requires knowing what could go wrong.
Practitioner Focus
Academic elegance means nothing if traders cannot act on the output. Every feature gets tested with working analysts before release. Complexity stays under the hood.
Continuous Research
Markets evolve. Models stagnate. The team dedicates twenty percent of every quarter
to exploratory research, testing new techniques before they appear in mainstream
literature.
Ethical Standards
The platform never tailors models to produce favorable backtests. All research
follows pre-registration protocols. Hypotheses get locked before data analysis
begins.
Recognition and Honors
Get in Touch
For questions about partnerships, media inquiries, academic collaborations, or institutional training programs, the team responds within two business days.
Phone
+64 (27) 0795 2040
content@linkiasneollipaefa.world
Office
Commercial Bay, 7 Queen Street, New Zealand